How to Choose Your Next E-Commerce Market? A Guide to 7 Markets in Europe
Spis treści
A good market for expansion is therefore not necessarily the one with the highest value of online sales or the largest share of e-commerce in total retail. What matters far more is whether, after accounting for all market-entry and ongoing operating costs, there is still enough room to maintain a healthy margin. From this perspective, two countries with similar sales potential can deliver completely different financial outcomes. One may require a larger investment in language and commercial localization, another may involve more expensive logistics or more complex returns management, while a third may impose additional obligations related to VAT, EPR, product safety, or information required when selling online. This is why the decision to expand should not begin with a ranking of the largest markets, but with an assessment of where a specific business model has the best chance of maintaining a positive margin after the real costs of operating in that market are taken into account.
In this guide, we compare seven European e-commerce markets: Germany, France, the Czech Republic, Slovakia, the United Kingdom, Poland, and the Netherlands. Each offers different opportunities and places different demands on sellers. The Czech Republic and Slovakia can be interesting markets for testing regional expansion, Germany provides access to a large and mature e-commerce market, France may require greater investment in language and commercial localization, while the United Kingdom, following Brexit, should be analysed as a separate sales model in which not only local VAT rules matter, but also export, import, shipment value, and whether sales take place through a company’s own online store or via a marketplace. The Netherlands, meanwhile, is a good example of how strongly local payment habits can affect conversion, while Poland combines a large e-commerce sector with highly developed payment and out-of-home delivery habits. The goal, therefore, is to identify a market where demand, margin, logistics, payments, localization, and compliance come together to create the conditions for profitable growth, rather than simply increasing the number of orders.
Is this guide for you?
This guide is primarily intended for companies that already have a functioning e-commerce sales model and see international expansion as the next stage of growth, rather than as an attempt to find the first market for an unproven product. If you already have stable sales in one or more EU countries, understand your margins, and are starting to look for another source of growth, several potential directions will usually emerge at the same time. Germany may be attractive because of its scale, the Czech Republic or Slovakia may offer a relatively manageable regional test for businesses operating nearby, France gives access to a large consumer base, the Netherlands is a mature digital market, Poland offers a sizeable and highly developed e-commerce environment, and the United Kingdom remains attractive despite more complex tax and customs rules. At this stage, the problem is no longer a lack of opportunities, but rather an excess of them. You need to decide which market should be tested first, where the sales potential is genuinely achievable, and whether the company has sufficient resources to meet local requirements without placing too much strain on the existing organization.
This article will also be useful if you want to compare market potential with the full cost of entry rather than with expected revenue alone. Before investing in a new version of your online store, campaigns, translations, integrations, or additional logistics, it is worth establishing whether customers expect different payment methods, what the local standards for delivery and returns look like, and what tax- and product-related obligations may arise. When selling to consumers in other EU countries, relevant factors may include how VAT and OSS are handled, as well as where the goods are actually stored and shipped from. On top of that come obligations related to packaging and EPR, product safety and labelling, documentation, warnings, and information required when selling online. If you are facing a choice between a neighbouring EU market, a large Western European market, and the United Kingdom, and want to assess these directions from the perspective of margin, risk, and scalability, this type of comparison will be far more useful than a simple ranking of e-commerce market size.
This guide will not simply answer the question: “where is e-commerce the largest?”
Market size matters, but in practice it should be one of several factors in the decision rather than the final deciding point. A large market can mean a large number of potential customers, but it can also come with stronger competition, higher customer acquisition costs, and more demanding service standards. This does not follow automatically from market size alone, because much depends on the product category, sales channel, brand positioning, and customer acquisition model, but it is a risk that needs to be included in the calculation. A company can therefore enter a highly attractive market, increase revenue, and still fail to achieve the expected level of profitability. This is particularly relevant for low-margin products, categories with high return rates, or assortments that are easy to compare on price with offers from local sellers. On the other hand, a smaller market may prove more profitable if the company can make better use of its existing logistics, keep customer acquisition costs at an acceptable level, and avoid having localization and customer service consume a large share of the margin.
A much better criterion is the fit between a market and the specific business. The same country can be an excellent destination for a premium brand with high margins and a low return rate, yet a poor choice for a seller of heavy, low-cost products where transport and return handling quickly absorb the profit. A market should also be assessed differently for a company fulfilling all orders from a warehouse in its home EU country than for a business planning local fulfilment or holding stock in another member state. In the case of B2C sales between EU countries, the intra-Community distance sales of goods rules and settlement through OSS may apply, whereas sales from a local warehouse to a customer in the same country constitute a different type of transaction and may involve local VAT obligations. The mere presence of a warehouse in another country should therefore not be reduced to one automatic conclusion, but it can undoubtedly change the structure of a company’s tax and operational obligations.
The United Kingdom should likewise be treated separately. It is not simply another European market with more paperwork. Selling goods from the EU to consumers in Great Britain involves export and import procedures, UK VAT, and rules that depend, among other things, on shipment value and the sales model. Direct sales through a company’s own online store may have different consequences from sales via a marketplace, which in certain situations assumes responsibility for collecting VAT. These differences show why market selection should include not only demand analysis, but also the logistics model, place of storage, sales channel, taxes, product requirements, and compliance costs. Only by bringing these elements together can a company answer the right question: not where it can sell the most, but where it has the best chance of building profitable and scalable sales.
What happens if you choose a market without this analysis?
High sales do not mean profitable expansion
A new market can improve the revenue chart very quickly while making the overall business less profitable. This happens when a company focuses primarily on the number of orders and total sales value, but does not separate financial performance by country. At the beginning of an expansion, it is easy to overlook costs that have already been optimized in the home market or are simply less visible there. Campaigns have to be launched from scratch, the brand has no established recognition yet, delivery may be more expensive, and handling returns can cost more than in the company’s existing markets. On top of that come localization costs, payment costs, additional customer service, compliance, and potential sales-channel commissions. If the product has a limited margin, just a few of these factors can be enough to make a market that looks attractive in terms of revenue much less attractive in terms of profit.
This is why expansion performance should not be assessed by revenue alone, but by the margin that remains after all costs associated with fulfilling an order in a given market. A company may sell more abroad than expected and still end up financing that growth with profits generated in its established markets. A particularly risky situation arises when customer acquisition costs are initially accepted as a market-entry expense, only to remain high even as sales scale. A similar problem can occur with discounts needed to compete with local sellers or with deliveries whose full cost has not been reflected in the price. Revenue is therefore not proof that an expansion has succeeded. Success begins when a company can acquire orders repeatedly on terms that leave enough margin to continue developing the market.
Customers may drop out before they even buy
A good product and a competitive price are not enough if the shopping experience feels unfamiliar to local customers or does not match their expectations. The checkout often becomes the critical moment. A customer may reach the final stage of an order and abandon it because they cannot find the payment method they expect, their preferred delivery option, or clear information about the delivery date. The same applies when prices are displayed only in a foreign currency, shipping costs are calculated in an unclear way, or the form does not match local addressing standards. Each of these elements increases uncertainty at exactly the point when the buyer should feel that the transaction will be simple and predictable. The problem may not be visible at the traffic level because campaigns can still generate visits to the website. It only becomes apparent through lower conversion rates and a rising cost per acquired order.
Weak language and commercial localization can have a similar effect. This is not just about whether product descriptions have been translated correctly. Customers also assess variant names, delivery information, terms and conditions, return policies, cart messages, transactional emails, and the way the store responds to questions after purchase. In categories where trust, safety, product fit, or detailed specifications matter, imprecise communication can reduce sales even when the product itself is attractive. Before entering a market, a company should therefore check not only whether it can technically accept orders from a given country, but also whether the entire buying process feels like a fully developed local offer rather than a foreign store that has simply enabled cross-border shipping.
The cost of returns can turn an attractive market into an unprofitable one
Returns are among the easiest costs to underestimate before sales begin. The cost of shipping an order to the customer is usually visible in the market-entry calculation, but the full cost of the process when a product comes back is much easier to miss. This includes return shipping, parcel handling, inspection of the product’s condition, putting it back into stock, potential repackaging, and the loss in value of goods that can no longer be sold as new. If the return is cross-border, costs may be even higher and the process may take longer. At the same time, customers expect simple rules, clear instructions, and fast refunds. Trying to reduce costs by making returns more difficult can therefore hurt conversion and the store’s reputation instead of improving sales economics.
The importance of this issue increases in categories where returns are a natural part of the buying process, for example when customers can only assess size, fit, appearance, or other product features after receiving the item. In such cases, even a small difference between the expected and actual return rate can materially change the profitability of a market. A company needs to determine where customers should send returned products, how much return shipping costs, whether a local return address makes business sense, and how long it takes for the product to become available for sale again. The business should therefore calculate not only the cost of delivering an order, but also the expected return cost allocated to each order. Only then can countries be compared on equal terms. A market with a high average order value may ultimately perform worse than a smaller market if reverse logistics and the percentage of returned products absorb a significant share of the margin.
Compliance gaps may only become visible once sales are already running
Compliance problems have one particularly unpleasant characteristic: they do not always prevent a company from starting to sell. A store may technically accept orders, campaigns may run, and revenue may grow even though the company has not identified all of its tax, environmental, or product-related obligations. Only after reaching a larger scale may it become clear that a particular sales model requires local registration, reporting, or additional product-related actions. Within the EU, it is necessary to distinguish, among other things, between goods shipped from one member state to consumers in another and sales fulfilled from a local warehouse in the destination country. In the first case, intra-Community distance sales rules and OSS may be relevant, while in the second, additional obligations may arise in connection with moving the company’s own goods and making domestic sales in the country where the warehouse is located.
The same applies to environmental and product-related obligations. Depending on the country and product category, there may be requirements relating to EPR, packaging, batteries, electronics, or other product groups. On top of that come product safety rules, required labelling, warnings, manufacturer or responsible-person details, and information that must be included in an online sales offer. Some of these requirements come from EU legislation, while others are implemented through local registration, reporting, or fee systems. If a company reviews them only after sales have started, the cost of market entry may turn out to be higher than expected, while correcting earlier periods may involve additional work, outstanding obligations, or the need to change processes quickly. Compliance should therefore be included in the market calculation before launch, not postponed until sales become significant.
The most expensive mistake: building the entire market before testing demand
Expansion becomes particularly expensive when a company treats market entry as a one-off implementation rather than a controlled test. A business can translate its entire product range, expand customer service, configure new logistics processes, sign agreements with additional partners, adapt its systems, launch broad campaigns, and only after several months discover that demand for the category is weaker than expected or that the local price needed to compete does not allow the expected margin to be maintained. The more fixed costs incurred before the first real sales data is available, the harder it becomes to walk away from a poor decision. A natural pressure appears to continue the project simply because the company has already invested heavily in it.
A safer approach is to treat each new country as a business hypothesis that needs to be validated first. This means defining in advance the minimum acceptable margin, customer acquisition cost, expected conversion rate, delivery and return costs, and the sales level at which further investment makes sense. The cost and time required to reach a meaningful market test are equally important. Two countries may offer similar margins per order once scale is achieved, but one may allow a test to be launched with a relatively small investment, while the other requires significantly more spending before demand can be assessed reliably for the first time. When choosing a market, a company should therefore look both at future unit economics and at the capital, time, and resources required to reach the point where those economics can actually be measured with confidence.
How to choose your next e-commerce market: start with 7 criteria
Demand and category potential
The first question should not be: “how large is e-commerce in this country?”, but rather: “how large and attractive is the market for my product?”. A high level of online shopping does not automatically mean strong demand in every category. Customer behaviour varies depending on the type of product, price level, age of the target audience, local brands, and the maturity of online sales within a specific segment. That is why the assessment of market potential should move from the level of the overall market down to the category level, and ideally even further, to the price range and type of offer the company actually intends to sell. It is worth checking whether consumers buy similar products online, what types of offers are visible in the most important sales channels, how broad the local selection is, and whether there are already brands on the market addressing the same customer need.
It is also important to distinguish demand from availability. A large number of similar offers may indicate a well-developed category, but it can just as easily signal a highly saturated market. Conversely, a smaller number of competitors is not always an opportunity, because it may simply reflect limited interest in the product. Competitor research should therefore be combined with an analysis of prices, category popularity, product visibility, and local customer behaviour. Analysing bestsellers and making test purchases from local sellers can be particularly useful, as it shows not only what they sell, but also how they present their offer, how much delivery costs, and what the overall shopping experience looks like. Demand should be assessed as close to the specific product as possible, rather than based on the general attractiveness of the country.
Margin and price levels
Sales potential only matters if the market allows you to achieve a price at which the economics of each order remain healthy. Before entering a market, you therefore need to establish not only how much similar products cost locally, but also what price is realistically achievable for a brand that does not yet have recognition in that market. Competitors’ list prices can create a misleading impression of strong margin potential if most sales happen during promotions or local sellers regularly compete through discounts. Differences in VAT, payment costs, delivery, returns handling, marketing, and compliance also need to be taken into account. A product that is profitable when sold in an existing market may have a completely different cost structure once these elements are added in another country.
The safest approach is to calculate the margin under several scenarios rather than rely on a single optimistic case. One scenario may assume the planned advertising cost and a moderate return rate, another higher customer acquisition costs, and a third the need for more aggressive price promotions. This makes it easier to see how much room there is for mistakes and cost fluctuations. Extra caution is needed with inexpensive, heavy, or bulky products, because transport costs can represent a significant share of the order value. Premium brands have a different risk profile: they may benefit from higher margins, but often require greater investment in communication and trust-building. The key is to determine whether the achievable price covers the full cost of expansion, not just the cost of the product and its initial shipment to the customer.
Competition
Competitor analysis should answer one specific question: why should a customer choose your new offer instead of one of the many alternatives already available? In some markets, price may be the main advantage, but a strategy based solely on being cheaper quickly erodes margins and makes sales dependent on promotions. A safer approach is to identify an area where the company brings something harder to copy: a better-designed product, higher quality, greater specialization, a unique bundle, stronger design, better variant availability, or more efficient service. It is also important to remember that competitors’ market position does not result from the product offer alone. Local companies may have an advantage based on brand recognition, reviews, logistics infrastructure, and long-standing customer relationships.
In practice, competitor research should go beyond a few stores ranking highly in search results. What matters is where customers actually begin their shopping journey: on brands’ own websites, marketplaces, local comparison sites, or other channels. You should compare prices, delivery costs, fulfilment times, return policies, number of reviews, breadth of assortment, and the way products are presented. A positive signal is finding a gap that the company can fill without drastically lowering prices. If the only available advantage is a lower price, the business needs to calculate whether it can sustain that position after adding local marketing and service costs. Competition should not be assessed simply as “high” or “low”, but in terms of whether the company has a realistic way to win customers without permanently sacrificing margin.
Logistics and returns
Logistics affects costs, conversion, and customer satisfaction at the same time, which is why it should not be analysed only as the price of a courier shipment from the company’s current warehouse. In different markets, consumers may prefer home delivery, pickup points, or parcel lockers, and the absence of a locally popular option can limit sales even if the store offers relatively inexpensive shipping. Delivery speed and predictability also matter. Customers usually compare a foreign store with local offers, not with other sellers shipping cross-border from the same origin country. If the local standard means fast delivery and convenient collection, a difference of several days can become a real purchasing barrier. That is why a company needs to check whether its current logistics infrastructure is competitive from the perspective of the target market, rather than merely technically capable of serving that country.
Returns are the second part of the same calculation. You need to determine where customers should send products back, how much return shipping costs, whether a local return address makes business sense, and how long it takes for the product to be returned to saleable stock. At a larger scale, local fulfilment may become an option. This can shorten both delivery and return times, but it also increases operational complexity and requires an analysis of the tax consequences of storing goods in another country. There is no single model that works for every store. A lightweight, high-value product can often be shipped cross-border efficiently for much longer than a large, low-cost product. Logistics should therefore be calculated as part of the economics of each individual order while also being assessed against customer expectations.
Payments
Payment is one of the final stages of the buying process, but its importance needs to be analysed before launching in a new market. Consumers in different countries have their own habits when it comes to completing transactions, and a payment method popular in one home market may play a much smaller role elsewhere. A customer who cannot find a familiar and trusted payment option may perceive the store as less credible or decide that the purchase is too inconvenient. Simply enabling card payments does not therefore always mean that the checkout is properly localized. You need to check which methods are genuinely expected in a given market, which are popular among the specific target audience, and what costs are associated with implementing and maintaining them.
Payment analysis should also include currency, the timing of payment collection, refund handling, and the impact of different methods on cash flow. Displaying prices in the target market’s currency makes it easier for customers to evaluate the offer and reduces uncertainty around currency conversion. From the seller’s perspective, however, transaction fees, exchange rates, and the handling of refunded amounts also need to be considered. Payments are therefore both part of the customer experience and part of order economics. If a local payment method significantly improves trust and conversion, not offering it can increase the effective customer acquisition cost even if advertising campaigns are performing well. Checkout should be treated as a localized part of the offer rather than as one universal process for all countries.
Taxes and compliance
Taxes and compliance need to be analysed together with the sales model, because obligations depend not only on the customer’s country, but also on where the goods are shipped from, how inventory is stored, and which sales channel is used. For B2C sales from one EU member state to consumers in other EU countries, the rules on intra-Community distance sales of goods and the common EU threshold of EUR 10,000 net, calculated collectively for transactions covered by that threshold, are relevant. Once the threshold is exceeded, the place of taxation for intra-Community distance sales is, as a rule, the member state where transport ends, while OSS allows this VAT to be reported through a single system rather than requiring local registrations solely because of the distance sales themselves. OSS does not, however, replace local VAT obligations that may arise from other elements of the operating model.
The situation is different when a company moves its own goods to a warehouse in another EU country and then sells them to local customers. Sales where transport begins and ends in the same country do not qualify as intra-Community distance sales and are generally subject to local VAT rules. Moving a company’s own goods into a warehouse in another member state may also trigger VAT obligations, which is why local fulfilment should be analysed before shipments begin. This is especially important when comparing a model in which all orders are dispatched from one existing EU warehouse with one based on holding stock closer to the customer. Faster delivery may offer a significant advantage, but it should be weighed against the additional administration, reporting, and costs involved in maintaining such a structure.
VAT is only one layer of compliance. Depending on the product and country, companies also need to check environmental obligations, including EPR, packaging requirements, and rules relating to specific product categories. Product safety, correct labelling, documentation, warnings, and information required for online sales are equally important. Since 13 December 2024, the GPSR has applied, introducing requirements for information presented when products are sold at a distance, including online, relating among other things to product identification, the manufacturer, and, where applicable, the responsible person in the European Union. The cost of adapting the offer and internal processes to these requirements should be included before the market test begins.
The United Kingdom requires a separate analysis because sales from the EU involve export and import procedures as well as local VAT rules, while the method of settlement depends, among other things, on shipment value and whether sales are made directly or through a marketplace. UK rules on low-value consignments and their taxation should not be treated as a permanent point of reference for many years, because import regulations are currently undergoing changes. When planning entry into the UK, the calculation should therefore be based on the rules in force at the time of implementation rather than on the simplified assumption that the tax and customs model will remain unchanged throughout the entire expansion period.
Localization
Localization starts with language, but it does not end there. Translating product names and a few key pages may be enough to launch a store technically, but not necessarily to create an experience that can compete with local sellers. Product descriptions, categories, checkout messages, transactional emails, terms and conditions, return policies, FAQs, and advertising materials all need to be adapted. Tone of voice and the way product benefits are presented also matter. An argument that works in one existing market may not have the same impact in another. This is particularly important for products that require greater trust or a more complex decision-making process, where customers carefully review specifications, warranty terms, delivery conditions, and return options before purchasing.
Localization also includes post-purchase support. If a customer has a question about an order, complaint or return, they expect a clear answer and an efficient resolution. A company therefore needs to assess whether it can provide customer service in the appropriate language and what organizational cost this will involve. In some markets, a greater investment in localization may be necessary from the start, while in others it may make sense to develop it gradually as sales grow. What matters is that the cost of this process is included in the calculation before the decision is made. A market may look attractive in terms of demand and logistics, but if effective sales require a substantial local team, large amounts of new content, and intensive customer support, its true entry barrier will be much higher than geography alone would suggest.
These seven criteria make it possible to compare the attractiveness of different markets, but before making a decision it is worth looking at two additional financial outcomes. The first is post-entry unit economics: the result of an individual order after taking into account product cost, advertising, payments, logistics, returns, and other variable costs. The second is the cost and time required to reach a reliable market test, including implementation, localization, required registrations, operational adjustments, and the resources needed before enough data is available to evaluate demand. Only by combining these two perspectives can you identify the market that is not only potentially profitable, but also sensible as the next step in your expansion.
Simple scoring: calculate which market really comes out ahead
Comparing several countries “by feel” quickly becomes problematic, because each of them may look attractive for a different reason. Germany may stand out for scale, the Czech Republic for the ease of running a regional test, France for the potential of specific categories, and the Netherlands for the maturity of online shopping. Without a common evaluation method, it is easy to give too much weight to whichever argument happens to support a conclusion you have already formed. A simpler solution is to score each market from 1 to 5 across the same seven areas. A score of 1 means conditions are highly unfavourable for the specific business, 3 means they are acceptable but require additional work or cost, and 5 means there is a very strong fit. The important point is to score not the “quality of the country”, but how well that country fits your own sales model. The same market may therefore receive 5 points for logistics from a store selling lightweight, high-value products from a nearby EU fulfilment hub and only 2 points from a company selling large, heavy, low-margin goods over longer cross-border distances.
Scoring should not replace financial calculations either. It is a tool for structuring the decision and identifying which markets are worth analysing in greater depth. Alongside the final score, it is therefore useful to record two additional parameters: expected unit economics once the business reaches a meaningful scale, and the cost and time required to reach a reliable market test. Two countries may achieve a similar overall score, but one may require only minor adaptations to existing processes, while the other needs a much larger budget for localization, compliance, integrations, and operations before the first meaningful data is available. For a company choosing its next market, rather than the theoretically best market at some point in the future, that difference can determine the decision.
Example weights
Demand can be given the highest weight, because even a perfectly organized operation cannot rescue a market where the product does not generate sufficient interest. An example model might assign 25% of the final score to demand, 20% to margin, 15% to competition, 15% to logistics, 10% to payments, 10% to compliance, and 5% to ease of localization. In each category, the market receives a score from 1 to 5, which is then multiplied by the relevant weight. For competition, a high score should indicate a favourable situation from the company’s perspective: a genuine opportunity to differentiate without entering a permanent price war. The same applies to compliance: 5 points does not mean more regulation, but rather that the requirements are relatively straightforward, predictable, and manageable within the given sales model.
| Criterion | Weight | What a high score means |
| Demand | 25% | Strong interest in the category and a realistic opportunity to sell the product online |
| Margin | 20% | Market pricing leaves sufficient margin after market-entry and operating costs |
| Competition | 15% | The company has a clear way to differentiate without excessive price pressure |
| Logistics | 15% | Delivery and returns are cost-competitive and meet customer expectations |
| Payments | 10% | Locally expected payment methods can be implemented without excessive cost or complexity |
| Compliance | 10% | Obligations are identified, predictable, and manageable at the planned scale |
| Ease of localization | 5% | The store, communication, and customer service can be adapted without disproportionate effort |
The weights are a starting point, not a universal standard. If two markets differ in their final score by only a few hundredths of a point, there is little value in pretending that the model has produced a clear winner. What matters much more is understanding where the difference comes from and which criteria are genuinely decisive for the specific business. A well-designed scoring model should also use the same assumptions for every country. If one market is assessed using bestseller prices, actual delivery costs, and local requirements, while another is judged only on general e-commerce market size, the results will not be comparable. Before assigning scores, it is therefore worth establishing one research method for each criterion and applying it consistently across all markets being analysed.
When should you change the weights?
A premium brand may reduce the importance of price itself and place greater weight on purchasing power, category potential, positioning, and the quality of the shopping experience. For inexpensive, heavy, or bulky products, logistics should carry significantly more weight, because a difference of just a few euros in delivery costs can completely change the margin on an order. For fashion and footwear, return economics become especially important, so it may make sense to increase the weight of logistics or introduce a separate return-risk score within it. In more heavily regulated categories, compliance should receive a higher weighting, particularly when market entry involves additional obligations related to product safety, labelling, EPR, packaging, or documentation required for online sales. In such a model, a market with strong demand may lose out to a smaller country if the cost of maintaining compliance absorbs a significant share of the expected margin.
A marketplace-first model will also require a different approach. In that case, greater weight should be given to the strength of the specific sales channel in the category, commissions, the cost of advertising within the platform, fulfilment rules, return conditions, and product documentation requirements. A market may be difficult for a new standalone online store while being relatively easier to test through an established marketplace, provided that implementation costs, compliance requirements, and the fulfilment model do not create a significant barrier to entry. In some categories, the platform may require specific product data, registration numbers, or proof of compliance before sales can begin, so a marketplace should not automatically be treated as a cheap and simple test. There is no single ranking of seven countries that works for every online store. A ranking only becomes meaningful once the weights reflect the economics of the specific business. If changing one key assumption completely reverses the order of the markets, that is a strong sign that this is the factor that needs the most careful validation before expansion begins.
7 e-commerce markets in Europe — a quick comparison
A comparison of Germany, France, the Czech Republic, Slovakia, the United Kingdom, Poland, and the Netherlands shows why it is difficult to create a universal order for expansion. Each of these markets can be a good choice, but for a different type of company and at a different stage of development. The Czech Republic can be a sensible place to run a controlled regional test for businesses that can serve it efficiently from existing EU infrastructure, while Germany offers access to a large and mature market but requires readiness to compete with local sellers and adapt the customer experience to local expectations. France may be attractive for brands prepared to invest more heavily in language and commercial localization, the Netherlands requires a checkout well adapted to local payment behaviour, and the United Kingdom should be analysed separately because of its import, tax, and customs model. Slovakia, meanwhile, may allow a company to reuse some of the processes and infrastructure developed earlier for regional expansion, particularly if it already operates in nearby Central European markets.
| Market | When it makes sense | Biggest advantage | Most important customer expectation | Biggest risk |
| Germany | When the company has a proven product, sufficient margin, and well-organized logistics and customer service | Large scale, mature demand, and strong access to the wider EU market | Credible local communication, transparent purchasing terms, and efficient delivery and returns | Strong competition and additional compliance obligations |
| France | When the brand has clear differentiators and can invest in broader localization | Potential for brands that can justify their positioning and price | Natural communication in the local language and an experience adapted to the market | Insufficient localization, marketing costs, and extensive environmental obligations in some categories |
| Czech Republic | When the company wants to run a controlled regional expansion test with manageable logistics | Relatively accessible market for many EU sellers and a useful test of localization capability | Local language, convenient out-of-home delivery, suitable payment methods, and easy comparison of purchasing terms | Price competition and the need to adapt the offer to local product discovery and comparison channels |
| Slovakia | When the company already has regional experience, particularly in Central Europe | Ability to reuse some of the processes and infrastructure developed for regional expansion | Local language, convenient delivery, and flexible payment options | Limited market size and the risk that local service costs will be too high relative to sales |
| United Kingdom | When the product has sufficient margin to support a more complex cross-border model | Large and developed e-commerce market | Clear pricing in local currency, efficient delivery, and a simple returns process | Import, VAT, customs issues, and changing rules for cross-border consignments |
| Poland | When the company sees clear category demand and can adapt to a market with strong price transparency and developed delivery habits | Large Central European e-commerce market with mature payment and out-of-home delivery behaviour | Fast payments, convenient out-of-home delivery, and high price transparency | Strong price competition and underestimating the need to adapt payment, delivery, and localization to local expectations |
| Netherlands | When the company has a well-functioning cross-border model and is ready to adapt its checkout | Mature digital market and highly developed online shopping | Locally preferred payment methods, transparent delivery, and a simple purchasing process | Lower conversion from an inadequately localized checkout and competition in a mature market |
The table is not a ranking from the best country to the worst. Its purpose is to show where the main sources of advantage and risk may lie from the perspective of a typical mid-sized EU e-commerce company. A business selling a lightweight, high-margin product with well-developed cross-border customer service may find the Netherlands easier to launch than the Czech Republic if its existing fulfilment setup and sales model fit Dutch conditions better. Conversely, a company selling large volumes of low-margin products may generate strong sales in Germany and still find the market unattractive once delivery costs, returns, and price competition are taken into account. For this reason, entire countries should not be labelled simply as “easy” or “difficult” markets. The company, the product, the location of its existing infrastructure, and the market-entry model determine the true complexity of expansion.
The most important difference between markets becomes visible when sales potential is compared with the real cost of launching a test. For some EU businesses, the Czech Republic or Slovakia may allow them to reach the first reliable data quickly, while for others Germany, France, Poland, or the Netherlands may be operationally easier because they can be served more efficiently from existing warehouses, teams, or commercial infrastructure. A larger initial cost does not automatically mean a worse decision if the potential margin and scale justify the investment. After the initial comparison, it is therefore worth recording three values for each market: its scoring result, the expected unit economics once the target operating model has been reached, and the budget and time required to run a reliable test. Only together do these show which country makes the most sense as the next step in expansion.
Germany — a large market for companies with well-organized processes
Germany is one of the most obvious expansion destinations for EU e-commerce businesses, but that is exactly why it is easy to overestimate how simple market entry will be. Its scale, central position in the EU, and well-developed logistics networks can reduce some operational barriers, particularly for companies already fulfilling orders from nearby member states. However, they do not solve the problems of competition, customer acquisition costs, or the need to provide a locally appropriate shopping experience. For a company that already has a proven product, well-organized logistics, a functioning returns process, and a budget that allows it to test the market without expecting immediate profitability, Germany can be a highly attractive direction. For a business that is still learning its own unit economics or solving basic operational problems in its existing markets, the same market can quickly expose every weakness in the model.
When can Germany be a good next market?
The best starting point is a product whose competitive advantage goes beyond a low price. That advantage may come from quality, design, specialization, a unique combination of features, availability of a specific variant, or a better way of solving the customer’s problem. The easier it is to compare the product with dozens of similar offers, the greater the risk that expansion will become a battle over price and advertising costs. Germany makes the most sense when a company can answer one question clearly: why should a customer choose its offer even though they do not yet know the brand? This requires not only a good product, but also enough margin to finance customer acquisition, returns handling, and local adaptation of the store without immediately resorting to price cuts.
The second condition is operational predictability. If delivery times from the company’s existing fulfilment location are stable, the business knows its shipping and return costs, can provide customer service in German, and has well-organized processes for complaints, terms and conditions, and product information, it becomes much easier to assess the true profitability of entering the market. As sales scale, other logistics models can be considered, but it should not be assumed that a local warehouse will automatically solve the competitiveness problem. Changing the fulfilment model may shorten delivery times, but it also increases fixed costs and may change the company’s tax obligations. Germany is therefore a good next market when the company is scaling a model that already works, rather than trying to build that model from scratch as part of the expansion.
What needs to be refined in the German customer experience?
In the German version of the store, it is particularly important to reduce customer uncertainty at every stage of the purchasing process. In practice, this means clear information about the product, price, delivery, returns, and seller details, as well as communication that does not feel like an automatically translated version of a foreign store. Customers should be able to understand easily what they are buying, when they will receive their order, how much delivery will cost, and what they can do if the product does not meet their expectations. In categories where purchasing requires greater trust or careful comparison of specifications, a lack of precise information can work against the seller before price even becomes the main decision criterion. Language localization should therefore cover not only the product page, but also the checkout, transactional messages, FAQ, returns policy, and after-sales service.
The post-purchase experience is equally important. Efficient delivery, easy access to shipment information, and a clear returns process form part of the overall offer rather than merely its logistical back end. An EU-based cross-border seller should therefore compare itself not with other foreign companies shipping into Germany, but with local sellers that customers see as direct alternatives. Local payment behaviour should also be analysed separately rather than assuming that a checkout designed for the company’s home market will work equally well after translation alone. The point is not to assign one behavioural pattern to all German consumers, but to determine which payment methods, delivery options, and service standards genuinely matter for the specific category and target group.
What can eat into the margin?
The first risk is customer acquisition cost in a category where the company has no existing brand recognition. A market with high potential attracts many sellers, which means that a good product does not guarantee cheap access to customers. If the offer is also easy to compare, there is a temptation to improve conversion through discounts. The company then starts paying twice: first for advertising and then through a lower selling price. On top of that come delivery and return costs, which in some categories can significantly reduce the profitability of an individual order. It is particularly risky to calculate profitability only on the basis of orders retained by customers while excluding returned products from the average cost of sales.
The second group consists of costs that are not visible in a basic marketing calculation. Selling in the German market may involve EPR obligations relating to packaging, including registration in LUCID and, depending on the type of packaging, participation in the relevant system and reporting packaging volumes. From 12 August 2026, foreign sellers without a branch in Germany that sell empty packaging or packaged products directly to end users should additionally verify whether they are required to appoint an authorised representative in Germany. Registration in LUCID itself remains the responsibility of the business. Depending on the product range, other product-related obligations may also apply, which is why compliance costs should be included before sales are scaled.
If the company decides to store goods in Germany, it also needs to analyse the VAT consequences of moving its own inventory from another EU member state and subsequently making local sales. OSS does not replace local VAT reporting for ordinary domestic sales fulfilled from a German warehouse. Each of these costs may be manageable on its own, but their combined impact matters for the margin. Before entering the market, it is therefore worth calculating not only advertising and shipping costs, but the full cost of operating once sales reach the point where the market is no longer a test and becomes a permanent revenue channel.
Who should not use Germany as their first test market?
The greatest risk applies to companies with low margins, an unproven product, or poorly organized operations. If the current model works only with low delivery costs, a small number of returns, and relatively inexpensive customer acquisition in the company’s existing markets, expansion may expose its limitations very quickly. The same applies to products whose only differentiator is price. The company then enters a larger market without a sustainable competitive advantage while simultaneously adding localization, advertising, logistics, and compliance costs. Instead of gaining profitable scale, it may simply generate more revenue at an increasingly lower margin. Germany is therefore not the best place to test whether a product makes business sense at all if the same hypothesis can be validated elsewhere at a lower cost and with fewer new processes.
Caution is also needed when an organization is not yet able to measure financial performance separately for each market. Without data on CAC, average order value, payment costs, delivery, returns, and contribution margin, growing sales can be interpreted as success for a long time even when the new country is not generating a positive financial result. Entering Germany simply because it is one of Europe’s largest e-commerce markets can accelerate problems rather than business growth. A much better time for expansion is when the company already knows its key metrics, has a budget for testing, and can define in advance which results will justify increasing investment and which will lead it to reduce or stop the project.
Best suited for: companies with a proven product, healthy margins, and processes ready to scale. Biggest risk: treating Germany’s market size and accessibility as sufficient justification for entering without first validating the economics of the sales model.
France — a market where half-measures in localization quickly become obvious
France can be an interesting direction for a company that does not want to compete on price alone and can build a convincing offer around its product. This is particularly true for brands where design, aesthetics, quality, specialization, or consistent positioning play an important role. At the same time, this is a market where simply providing a French-language version should not be confused with full localization. You need to look at the entire process, from the first interaction with an advertisement, through the product description and checkout, to post-purchase messages, customer service, and returns. This requires more discipline than mechanically translating content originally created for another market.
When does France make sense?
France can be a good direction for brands that have a clear reason to exist alongside local competitors. If the value of the product is tied to design, build quality, a particular style, specialization, or the broader brand experience, the company has more ways to build an advantage than in a situation where customers compare mainly price and basic specifications. This does not mean that every premium product will automatically find buyers in France. The key is to assess the potential of the specific category, local price levels, and the strength of brands already addressing the same customer need. The more important trust and brand perception are in the purchase decision, the larger the role communication plays in the investment, rather than simply the technical launch of sales.
Before entering the market, the company should therefore determine whether it can translate its positioning into the French context without losing what makes the product attractive in the first place. If sales in the company’s existing markets rely mainly on aggressive performance marketing and promotions, there is no guarantee that the same model will deliver similar results after the campaigns are simply translated. France makes more sense when the company has enough budget to test both demand itself and the way the offer is communicated. Margin is also important, because the cost of localization and acquiring the first customers may be higher than in a market where only minor adaptations to the existing infrastructure are required.
Why is translating the store not enough?
Providing key information in French is not purely a marketing issue. French regulations require the use of the French language, among other things, when presenting and offering products and when providing information that consumers need to assess the product and use it safely. However, this level should be clearly distinguished from full commercial localization. Meeting the requirement to provide relevant information in French does not mean that the brand’s communication has been adapted to the market. Full localization also includes sales arguments, advertising, content structure, transactional messages, customer service, and the way communication is handled after purchase.
Customers see the entire purchasing journey, and at every stage they may encounter signals that the offer was not prepared with them in mind. This applies to category names, product descriptions, advertising, delivery terms, return policies, cart messages, forms, and customer service responses. Even a linguistically correct translation may be ineffective if it preserves the structure of the sales argument and communication style created for another market. For products whose value is partly driven by brand image, inconsistent or unnatural communication can weaken the customer’s confidence that they are dealing with a professional seller. Localization should therefore be treated both as a requirement related to providing certain information correctly and as a separate business decision about how deeply the company wants to adapt the shopping experience to the market.
What needs to be considered beyond marketing?
Entering France also requires looking at compliance. Obligations related to extended producer responsibility can be particularly important, as the French system covers many product and packaging categories. Depending on the assortment, a company may need appropriate registration, identification, reporting, and settlement of environmental obligations. From an e-commerce perspective, it is important to remember that these requirements do not apply only to traditional manufacturers operating through physical channels. Online and cross-border sales may also fall within their scope. Before launching the market, the company should therefore establish which EPR streams apply to the product and packaging, and what administrative and financial costs will be involved in meeting these requirements correctly.
On top of that come EU product requirements, including safety rules, information presented in distance selling, and appropriate labelling and documentation. If the company sells products in categories subject to additional regulations, the analysis needs to be carried out at the level of the specific assortment rather than for the store as a whole. It is worth comparing compliance costs with the cost of full localization, because both arise independently of advertising spend. A market may therefore have attractive sales potential while still requiring a larger investment before scale is reached. The better the company understands these costs before launch, the easier it is to determine the level of sales required for France to become economically justified.
The biggest risk
The most difficult scenario arises when the product is easy to compare, the brand has no existing recognition, and customer acquisition turns out to be more expensive than expected. The company may try to compensate with promotions, but this means that marketing costs rise while margins fall at the same time. If competitors also offer a similar product with fast delivery and communication well adapted to the market, a foreign seller needs a very specific reason why customers should choose its offer. The fact that the product sells well in another EU market is not enough. Before entering France, the company needs to understand whether there is a genuine market gap and whether the brand can exploit it without permanently subsidizing sales through advertising.
The second risk is treating localization as a one-off project that ends when the French version of the store goes live. In practice, as sales grow, content needs to be updated, customer questions need to be handled, problems need to be resolved, campaigns need to be developed, and product information needs to remain compliant. If the company has not planned resources for this stage, a market that initially looked attractive may start generating increasing amounts of manual work. This type of market entry will therefore be easier for a company prepared to localize its communication and customer service more deeply than for one that assumes the market can be run with almost no changes to existing processes. The difference concerns not only the quality of marketing, but also the ongoing cost of maintaining the market after the initial launch.
Best suited for: brands with a clear differentiator that are prepared to invest in localization and adapt the sales process accordingly. Biggest risk: treating France as an existing store simply translated into French, without accounting for the costs of localization, compliance, and customer acquisition.
Czech Republic — a sensible pilot market for European e-commerce
The Czech Republic can be a sensible expansion market for EU-based online stores because it combines a well-developed e-commerce environment with enough local specificity to genuinely test a company’s ability to sell beyond its existing markets. For businesses operating from nearby EU countries, cross-border logistics can often be managed without immediately building new local infrastructure, while the language difference and distinct shopping behaviours mean that simply enabling shipping to the Czech Republic and launching campaigns is not enough. Language, currency, the way the offer is presented, payments, and logistics all need to be adapted. This makes the Czech Republic a useful pilot market for many European sellers: operational complexity can remain manageable, while the market still requires real localization and forces the company to test whether its expansion process works outside the environment it already knows.
Why is the Czech Republic often suitable for a first test?
One of the Czech Republic’s main advantages is that many EU-based sellers can run a relatively controlled experiment without immediately building an entirely new infrastructure. Depending on the location of the company’s existing warehouse, goods may be shipped cross-border while some warehouse, technology, and operational processes remain unchanged, meaning stock does not necessarily need to be moved into a local warehouse from day one. This makes it possible to separate several key questions: is there demand for the product, do customers accept the proposed price, what does the cost of acquiring an order look like, and does localization improve conversion? For a mid-sized company, this can be valuable because the test does not always require a full capital commitment or a radical change to the logistics model from the outset.
At the same time, the Czech Republic should not be treated as an extension of another Central European market. It has its own shopping standards, local channels for product discovery and comparison, and its own expectations around payments and delivery. That is precisely what makes it a good test of organizational maturity. If a company can prepare a Czech version of its offer, adapt the checkout, take care of local communication, and measure performance separately for that market, it develops a process that can later be reused in other countries. If, on the other hand, sales only work when customers behave exactly like those in the company’s home market, problems will appear quickly and the expansion model can still be corrected before the business commits significantly more resources.
What is crucial for conversion?
The foundation is a complete Czech-language version that covers not only product pages, but also the cart, delivery information, return policies, transactional messages, and customer service. Prices should be displayed in the local currency so that customers can immediately assess the attractiveness of the offer without having to convert the order value themselves. Logistics are equally important. Out-of-home delivery, including pickup points and parcel lockers, plays an important role in Czech e-commerce, so the store should check whether its current delivery model matches what customers expect when completing a purchase. The ability to ship cross-border is not enough if the process turns out to be less convenient than local alternatives.
Payments should be approached in the same way. Customers use different methods to complete purchases, so instead of assuming that solutions working well in the company’s existing markets will also be sufficient in the Czech Republic, the business should verify the popularity of individual payment methods within the specific category and customer group. This also applies to cash on delivery, whose importance should be assessed using current data rather than relying on stereotypes about the Czech market. In practice, checkout should form part of the market test: if traffic and product interest are strong but conversion drops only when the customer reaches delivery or payment selection, the problem may not be demand itself but a purchasing process that is not sufficiently adapted to local expectations.
Why do you need to be careful with pricing?
Comparison engines and other channels that make it easy to compare offers play an important role in Czech e-commerce, which means that price, delivery cost, and seller ratings are easy for customers to compare. This does not mean the strategy has to be based on being the cheapest, but it does mean the price needs to be well justified. If a product costs more than comparable alternatives, customers should be able to understand immediately what they are paying extra for. That may be quality, specialization, a better variant, a broader bundle, availability, or more reliable service. Without such a differentiator, a company can easily fall into discounting that improves conversion while undermining the economics of the entire expansion.
Customers may use local stores as well as channels for discovering and comparing products, so checking only a few of the largest competitors is not enough before entering the market. The company needs to see what prices actually appear in the category, how often promotions are used, how much delivery costs, and how quickly customers receive their orders. Only against that background can an EU-based seller assess whether there is room for a healthy margin. If the price required to maintain profitability is higher than the level visible in competing offers, the company should have a concrete product or brand argument to support it. Otherwise, a high number of orders may be achievable mainly through discounts, which may confirm interest in the product but not the ability to scale profitably.
What can the Czech Republic help you test?
The Czech Republic is valuable above all because it allows a company to test whether it can manage genuine localization rather than just cross-border selling. The distinction matters. Cross-border sales may mean nothing more than accepting orders from another country and shipping them from an existing EU warehouse. Localization, by contrast, requires adapting the language, currency, checkout, payments, delivery, advertising, customer service, and the way the product is presented. If a company can go through this process in the Czech Republic, document its decisions, and measure the impact of individual changes, it builds a capability that can later be used when expanding into larger or more complex markets.
It is also a good moment to check whether the organization can separate the results of the new country from the results of the business as a whole. It should know its customer acquisition cost, average order value, margin after delivery and returns, the share of individual payment methods, and the impact of localization on conversion. Without this data, the test may end with nothing more than the conclusion that “there are sales” or “there are no sales”, which says very little about why the result looks the way it does. The Czech Republic can therefore serve not only as a test of demand, but also as a test of the expansion process itself: can the company prepare a market, measure it separately, and use the data to decide whether to scale the investment?
VAT when shipping from one EU country to the Czech Republic and Slovakia
If the goods remain in a warehouse in one EU member state and are shipped from there to consumers in the Czech Republic or Slovakia, such sales may qualify as intra-Community distance sales of goods. If the relevant conditions are met, once the common EU threshold of EUR 10,000 net for transactions covered by that threshold is exceeded, the place of taxation is generally the country of consumption. VAT on such sales can be settled through OSS instead of registering locally in each country solely because of intra-Community distance sales. This is an important distinction because simply starting to sell to Czech or Slovak consumers does not automatically mean that local VAT registration is required. The situation changes when the company moves its own stock to a warehouse in the Czech Republic or Slovakia. The movement of goods and subsequent local sales then require a separate VAT analysis, which is why decisions about local fulfilment should not be based solely on delivery cost and speed.
Best suited for: companies that want to run a controlled expansion test in a market that may still be served through existing EU logistics while requiring meaningful local adaptation. Biggest risk: assuming that regional proximity or familiarity means similar shopping behaviour and that an existing sales model can simply be transferred without local adjustment.
Slovakia — when regional synergy justifies the next market
Slovakia can be a logical next step after the Czech Republic, particularly when a company has already built some of the processes needed to serve Central Europe. This does not mean, however, that the two markets can be treated as one project differentiated only by the language of the store. Slovakia operates at a smaller scale, while price levels, demand structure, and shopping behaviour need to be verified separately for the specific category. This makes the economics of market entry especially important. The cost of launching a local version, campaigns, customer service, and compliance needs to remain proportional to the potential level of sales. For a company with well-prepared regional infrastructure, Slovakia can be an attractive complementary market, but for a business building every process from scratch, the relationship between localization costs and market size may be less favourable.
When is Slovakia particularly attractive?
Slovakia can be especially interesting when a company already has experience from regional expansion and does not need to incur all organizational costs from the beginning. If it already serves the Czech Republic or other nearby Central European markets, some knowledge of logistics, managing international campaigns, monitoring performance, and the localization process may already be present within the organization. This does not automatically mean lower costs in every category, but it shortens the list of things the company still needs to learn. The benefit can be particularly visible for lightweight products that are easy to ship and do not require complex reverse logistics, because this type of model is easier to operate cross-border from an existing warehouse.
The market can also make sense for companies that do not need massive scale to justify localization. If the product has a healthy margin, a low return rate, and a clearly defined target audience, the smaller size of the market does not have to be a problem. What matters is setting realistic expectations for category potential. Slovakia should not be selected simply because it is “next to the Czech Republic” or because the company already operates elsewhere in the region. Prices, competition, customer acquisition costs, and shopping behaviour all need to be checked separately. Only if these elements work together does regional synergy become an argument that strengthens the decision rather than its sole justification.
How can regional synergy be used?
The greatest savings can be achieved in areas where processes do not need to be built from scratch. A company can reuse some of the experience gained while configuring deliveries, managing returns, reporting campaign performance, analysing data, and organizing the work of the team responsible for expansion. With a similar operating model, it may also be easier to plan regional sales from a single EU warehouse and maintain shared technology and analytics processes. This is where synergy should be sought. It should not, however, mean copying content, prices, campaigns, or assumptions about customer behaviour. Each of these elements should be verified separately.
A dedicated language version and a separate pricing policy are particularly important. Similarity between languages does not mean that Czech communication will be appropriate for Slovak customers, just as price levels accepted in the Czech Republic will not automatically match what can be achieved in Slovakia. Payments and delivery should also be assessed separately, including the availability and cost of home delivery, pickup points, and parcel lockers. Logistics convenience should therefore be included in the market-entry model, but the dominant delivery method should not be assumed in advance without checking current data. Regional synergy is most valuable when it reduces the cost of the operational back end, but it does not replace local market analysis.
The biggest limitation
One of the most important limitations of Slovakia from an expansion perspective is its relatively smaller market size. This means that even a well-performing model may have a lower sales ceiling than in larger countries, making control over fixed costs particularly important. If the company needs a separate team, numerous new integrations, extensive customer service, and a large marketing budget before obtaining the first meaningful data, the payback period may become unattractive. This does not mean that a smaller market is inherently worse. The problem arises when the cost of building and maintaining a local presence remains high relative to the sales that can realistically be achieved.
Slovakia should therefore be assessed particularly carefully in terms of the cost of reaching a meaningful test and the cost of maintaining the market after launch. If existing infrastructure can be reused, logistics can be operated efficiently from an existing EU warehouse, and local customer service can be prepared with relatively limited investment, the economics may look attractive. If every element has to be built from the beginning, even good unit economics on an individual order may not be enough to recover fixed costs quickly. This is a market where the difference between the questions “are we making money on each order?” and “is the market generating enough total margin to justify the cost of maintaining it?” becomes especially clear.
Best suited for: companies that already have regional experience and can reuse some of their existing processes, logistics, and operational knowledge. Biggest risk: copying a strategy from the Czech Republic or another nearby market one-to-one without separately validating demand, pricing, payments, logistics, and the cost of maintaining a local presence.
Czech Republic — a sensible pilot market for European e-commerce
The Czech Republic can be a sensible expansion market for EU-based online stores because it combines a well-developed e-commerce environment with enough local specificity to genuinely test a company’s ability to sell beyond its existing markets. For businesses operating from nearby EU countries, cross-border logistics can often be managed without immediately building new local infrastructure, while the language difference and distinct shopping behaviours mean that simply enabling shipping to the Czech Republic and launching campaigns is not enough. Language, currency, the way the offer is presented, payments, and logistics all need to be adapted. This makes the Czech Republic a useful pilot market for many European sellers: operational complexity can remain manageable, while the market still requires real localization and forces the company to test whether its expansion process works outside the environment it already knows.
Why is the Czech Republic often suitable for a first test?
One of the Czech Republic’s main advantages is that many EU-based sellers can run a relatively controlled experiment without immediately building an entirely new infrastructure. Depending on the location of the company’s existing warehouse, goods may be shipped cross-border while some warehouse, technology, and operational processes remain unchanged, meaning stock does not necessarily need to be moved into a local warehouse from day one. This makes it possible to separate several key questions: is there demand for the product, do customers accept the proposed price, what does the cost of acquiring an order look like, and does localization improve conversion? For a mid-sized company, this can be valuable because the test does not always require a full capital commitment or a radical change to the logistics model from the outset.
At the same time, the Czech Republic should not be treated as an extension of another Central European market. It has its own shopping standards, local channels for product discovery and comparison, and its own expectations around payments and delivery. That is precisely what makes it a good test of organizational maturity. If a company can prepare a Czech version of its offer, adapt the checkout, take care of local communication, and measure performance separately for that market, it develops a process that can later be reused in other countries. If, on the other hand, sales only work when customers behave exactly like those in the company’s home market, problems will appear quickly and the expansion model can still be corrected before the business commits significantly more resources.
What is crucial for conversion?
The foundation is a complete Czech-language version that covers not only product pages, but also the cart, delivery information, return policies, transactional messages, and customer service. Prices should be displayed in the local currency so that customers can immediately assess the attractiveness of the offer without having to convert the order value themselves. Logistics are equally important. Out-of-home delivery, including pickup points and parcel lockers, plays an important role in Czech e-commerce, so the store should check whether its current delivery model matches what customers expect when completing a purchase. The ability to ship cross-border is not enough if the process turns out to be less convenient than local alternatives.
Payments should be approached in the same way. Customers use different methods to complete purchases, so instead of assuming that solutions working well in the company’s existing markets will also be sufficient in the Czech Republic, the business should verify the popularity of individual payment methods within the specific category and customer group. This also applies to cash on delivery, whose importance should be assessed using current data rather than relying on stereotypes about the Czech market. In practice, checkout should form part of the market test: if traffic and product interest are strong but conversion drops only when the customer reaches delivery or payment selection, the problem may not be demand itself but a purchasing process that is not sufficiently adapted to local expectations.
Why do you need to be careful with pricing?
Comparison engines and other channels that make it easy to compare offers play an important role in Czech e-commerce, which means that price, delivery cost, and seller ratings are easy for customers to compare. This does not mean the strategy has to be based on being the cheapest, but it does mean the price needs to be well justified. If a product costs more than comparable alternatives, customers should be able to understand immediately what they are paying extra for. That may be quality, specialization, a better variant, a broader bundle, availability, or more reliable service. Without such a differentiator, a company can easily fall into discounting that improves conversion while undermining the economics of the entire expansion.
Customers may use local stores as well as channels for discovering and comparing products, so checking only a few of the largest competitors is not enough before entering the market. The company needs to see what prices actually appear in the category, how often promotions are used, how much delivery costs, and how quickly customers receive their orders. Only against that background can an EU-based seller assess whether there is room for a healthy margin. If the price required to maintain profitability is higher than the level visible in competing offers, the company should have a concrete product or brand argument to support it. Otherwise, a high number of orders may be achievable mainly through discounts, which may confirm interest in the product but not the ability to scale profitably.
What can the Czech Republic help you test?
The Czech Republic is valuable above all because it allows a company to test whether it can manage genuine localization rather than just cross-border selling. The distinction matters. Cross-border sales may mean nothing more than accepting orders from another country and shipping them from an existing EU warehouse. Localization, by contrast, requires adapting the language, currency, checkout, payments, delivery, advertising, customer service, and the way the product is presented. If a company can go through this process in the Czech Republic, document its decisions, and measure the impact of individual changes, it builds a capability that can later be used when expanding into larger or more complex markets.
It is also a good moment to check whether the organization can separate the results of the new country from the results of the business as a whole. It should know its customer acquisition cost, average order value, margin after delivery and returns, the share of individual payment methods, and the impact of localization on conversion. Without this data, the test may end with nothing more than the conclusion that “there are sales” or “there are no sales”, which says very little about why the result looks the way it does. The Czech Republic can therefore serve not only as a test of demand, but also as a test of the expansion process itself: can the company prepare a market, measure it separately, and use the data to decide whether to scale the investment?
VAT when shipping from one EU country to the Czech Republic and Slovakia
If the goods remain in a warehouse in one EU member state and are shipped from there to consumers in the Czech Republic or Slovakia, such sales may qualify as intra-Community distance sales of goods. If the relevant conditions are met, once the common EU threshold of EUR 10,000 net for transactions covered by that threshold is exceeded, the place of taxation is generally the country of consumption. VAT on such sales can be settled through OSS instead of registering locally in each country solely because of intra-Community distance sales. This is an important distinction because simply starting to sell to Czech or Slovak consumers does not automatically mean that local VAT registration is required. The situation changes when the company moves its own stock to a warehouse in the Czech Republic or Slovakia. The movement of goods and subsequent local sales then require a separate VAT analysis, which is why decisions about local fulfilment should not be based solely on delivery cost and speed.
Best suited for: companies that want to run a controlled expansion test in a market that may still be served through existing EU logistics while requiring meaningful local adaptation. Biggest risk: assuming that regional proximity or familiarity means similar shopping behaviour and that an existing sales model can simply be transferred without local adjustment.
Slovakia — when regional synergy justifies the next market
Slovakia can be a logical next step after the Czech Republic, particularly when a company has already built some of the processes needed to serve Central Europe. This does not mean, however, that the two markets can be treated as one project differentiated only by the language of the store. Slovakia operates at a smaller scale, while price levels, demand structure, and shopping behaviour need to be verified separately for the specific category. This makes the economics of market entry especially important. The cost of launching a local version, campaigns, customer service, and compliance needs to remain proportional to the potential level of sales. For a company with well-prepared regional infrastructure, Slovakia can be an attractive complementary market, but for a business building every process from scratch, the relationship between localization costs and market size may be less favourable.
When is Slovakia particularly attractive?
Slovakia can be especially interesting when a company already has experience from regional expansion and does not need to incur all organizational costs from the beginning. If it already serves the Czech Republic or other nearby Central European markets, some knowledge of logistics, managing international campaigns, monitoring performance, and the localization process may already be present within the organization. This does not automatically mean lower costs in every category, but it shortens the list of things the company still needs to learn. The benefit can be particularly visible for lightweight products that are easy to ship and do not require complex reverse logistics, because this type of model is easier to operate cross-border from an existing warehouse.
The market can also make sense for companies that do not need massive scale to justify localization. If the product has a healthy margin, a low return rate, and a clearly defined target audience, the smaller size of the market does not have to be a problem. What matters is setting realistic expectations for category potential. Slovakia should not be selected simply because it is “next to the Czech Republic” or because the company already operates elsewhere in the region. Prices, competition, customer acquisition costs, and shopping behaviour all need to be checked separately. Only if these elements work together does regional synergy become an argument that strengthens the decision rather than its sole justification.
How can regional synergy be used?
The greatest savings can be achieved in areas where processes do not need to be built from scratch. A company can reuse some of the experience gained while configuring deliveries, managing returns, reporting campaign performance, analysing data, and organizing the work of the team responsible for expansion. With a similar operating model, it may also be easier to plan regional sales from a single EU warehouse and maintain shared technology and analytics processes. This is where synergy should be sought. It should not, however, mean copying content, prices, campaigns, or assumptions about customer behaviour. Each of these elements should be verified separately.
A dedicated language version and a separate pricing policy are particularly important. Similarity between languages does not mean that Czech communication will be appropriate for Slovak customers, just as price levels accepted in the Czech Republic will not automatically match what can be achieved in Slovakia. Payments and delivery should also be assessed separately, including the availability and cost of home delivery, pickup points, and parcel lockers. Logistics convenience should therefore be included in the market-entry model, but the dominant delivery method should not be assumed in advance without checking current data. Regional synergy is most valuable when it reduces the cost of the operational back end, but it does not replace local market analysis.
The biggest limitation
One of the most important limitations of Slovakia from an expansion perspective is its relatively smaller market size. This means that even a well-performing model may have a lower sales ceiling than in larger countries, making control over fixed costs particularly important. If the company needs a separate team, numerous new integrations, extensive customer service, and a large marketing budget before obtaining the first meaningful data, the payback period may become unattractive. This does not mean that a smaller market is inherently worse. The problem arises when the cost of building and maintaining a local presence remains high relative to the sales that can realistically be achieved.
Slovakia should therefore be assessed particularly carefully in terms of the cost of reaching a meaningful test and the cost of maintaining the market after launch. If existing infrastructure can be reused, logistics can be operated efficiently from an existing EU warehouse, and local customer service can be prepared with relatively limited investment, the economics may look attractive. If every element has to be built from the beginning, even good unit economics on an individual order may not be enough to recover fixed costs quickly. This is a market where the difference between the questions “are we making money on each order?” and “is the market generating enough total margin to justify the cost of maintaining it?” becomes especially clear.
Best suited for: companies that already have regional experience and can reuse some of their existing processes, logistics, and operational knowledge. Biggest risk: copying a strategy from the Czech Republic or another nearby market one-to-one without separately validating demand, pricing, payments, logistics, and the cost of maintaining a local presence.
The Netherlands — a market where checkout can determine success
The Netherlands is a digitally mature market where an EU-based online store can run cross-border sales relatively efficiently, provided it does not treat the local checkout as a copy of the solution used in its existing markets. Payments are particularly important here because Dutch consumers are strongly accustomed to local methods that allow them to pay directly from their bank account. In 2025, iDEAL remained the dominant online payment method in the Netherlands, accounting for around 70% of e-commerce transactions. At the same time, the market is currently going through a transition from iDEAL to iDEAL | Wero. For sellers, this means that adapting payment methods is not a one-off integration, but an element that needs to be monitored as the local payments ecosystem evolves.
When is the Netherlands an attractive market?
The Netherlands can be an interesting market primarily for companies that already have experience with cross-border sales and can efficiently adapt checkout, communication, and logistics to local conditions. It is not a market where testing a completely immature operating model is particularly attractive. A much better fit is a company that already knows how much customer acquisition costs, can measure margin after returns and delivery, and has processes that allow local payment methods to be implemented without rebuilding the entire store. The Netherlands can also be attractive for brands that can fulfil cross-border orders while maintaining short and predictable delivery times. The fact that the market is highly digitalized and well connected to the rest of the EU does not, however, mean that launching an English-language version of the store and simply adding the Netherlands to the list of shipping destinations will be enough.
The relationship between sales potential and localization cost also matters. If the company sells lightweight products, has healthy margins, and can serve the market efficiently from an existing EU warehouse, a test may require less investment than building local logistics infrastructure from day one. However, delivery times and return conditions still need to be checked against locally available offers. The Netherlands is therefore a good direction when a company already has a stable cross-border engine and can adapt its local components, such as payment methods, currency, communication, or delivery, without losing control over order economics.
Why are local payment methods so important?
In the Netherlands, a local payment method should not be treated as just another button in the checkout. It is part of the core shopping experience. iDEAL built a very strong position in Dutch e-commerce over many years and in 2025 accounted for the clear majority of online payments. This means that a store limited to cards or a few global payment methods may technically allow customers to buy, while still differing from the way a large share of consumers are used to completing transactions. From the seller’s perspective, the problem may only become visible at the very end of the funnel: the advertising works, the product generates interest, the user adds it to the cart, and conversion drops at the payment stage.
At the same time, the market is transitioning from iDEAL towards Wero. The migration process began in 2026 and is expected to continue over the following years, so companies should make sure their payment provider can support the change without disrupting checkout performance. The point is not to follow every technical stage of the migration internally, but to make sure responsibility for the local checkout is clearly assigned and reviewed regularly. For an e-commerce manager, the key question is therefore not “do we offer online payments?”, but “do we offer the payment method local customers actually expect, and will that method remain up to date as the market standard changes?”.
What else matters beyond payments?
A good checkout will not compensate for poor delivery or an unclear returns policy. Before buying, customers should know when they will receive their order, how much shipping will cost, and what the return process will look like. Especially when selling cross-border from another EU country, it is worth checking whether the promised delivery time is realistic and whether the store is competing with local sellers mainly on price while offering noticeably slower fulfilment. It is equally important to show the full purchase cost before the order is completed. Transparency around price, delivery, and returns reduces the risk that customers abandon the purchase at the final stage or later feel that the terms were different from what they expected.
Post-purchase support also needs to be planned. If a parcel is delayed, the customer wants to change the address, or a product needs to be returned, the response should be fast and easy to understand. As sales scale, the company should assess whether handling returns directly back to its existing EU warehouse is still economical or whether a local consolidation point becomes more cost-effective. Such a decision should not be based on logistics convenience alone, however, because local warehousing or holding stock in the Netherlands may change VAT obligations. The Netherlands therefore illustrates particularly well that efficient cross-border expansion is the result of several well-aligned elements: payments, delivery, returns, customer service, and the right tax model.
Best suited for: online stores with a mature cross-border model that can adapt checkout and customer service locally without losing control over margins. Biggest risk: launching a global checkout without accounting for local payment methods and assuming that the technical ability to place an order means the store is fully adapted to the market.
Formalities: what is common across the EU, and what needs to be checked locally?
Expansion within the European Union gives a company access to the single market, but it does not mean that every country has an identical set of obligations. Some rules, such as those governing distance sales or product safety, stem from EU legislation. Other obligations are implemented through national registers, EPR systems, local VAT procedures, or specific requirements relating to language and consumer information. Compliance therefore needs to be analysed on two levels at the same time. First, the company should establish which rules arise from its sales model within the EU, and then check what additional requirements apply in the specific country and to the specific type of product. The biggest problems tend to arise when a company understands the general EU rules and assumes they automatically cover every local obligation.
VAT and OSS
Under a standard model where goods remain in a warehouse in one EU member state and are shipped to consumers in other EU countries, the sales may qualify as intra-Community distance sales of goods. For transactions covered by the EU threshold, there is one common limit of EUR 10,000 net rather than a separate threshold for each country. Once that threshold is exceeded, the place of taxation for intra-Community distance sales is generally the country where transport of the goods ends. OSS then allows VAT due in individual countries of consumption to be reported through a single system rather than requiring local registration in every country solely because the business is making intra-Community distance sales. This is particularly important for cross-border e-commerce businesses, because starting sales in another EU member state does not in itself mean that a separate local VAT registration is automatically required there.
The situation changes when the company modifies its logistics model. If its own goods are moved from one EU member state to a warehouse in another, local VAT obligations may arise as a result of the stock transfer itself. Subsequent sales where transport begins and ends in the same country do not qualify as intra-Community distance sales and are generally subject to local VAT rules. OSS does not replace these obligations. A decision to move from cross-border fulfilment out of an existing EU warehouse to local fulfilment in the target country should therefore be preceded by a tax analysis, not just a logistics assessment. In practice, the first question should be: where are the goods physically located before the sale, and where are they being transported? Only on that basis can the correct VAT model be determined.
EPR and environmental obligations
Environmental obligations are among the elements of expansion that cannot safely be copied from one market to another. Extended producer responsibility covers different product and packaging streams, while the way registration, reporting, and fees are handled may vary from country to country. A company selling the same product in Germany and France may therefore be subject to the same general concept of environmental responsibility while fulfilling its obligations through different systems, registers, and procedures. The scope of EPR also depends on the product range. Separate requirements may apply to packaging itself, electrical equipment, batteries, textiles, or other categories covered by specific responsibility schemes.
EPR should therefore not be reduced to a single question: “are we registered?”. The company needs to determine who is considered the obligated party under the given model, which product and packaging categories are covered, whether registration or participation in an appropriate organization or system is required, and whether quantities must be reported and fees paid. It may also matter whether the company has a branch in the country and whether it sells directly to consumers. Germany is a good example of how these regulations evolve: from August 2026, foreign sellers without a branch in Germany should, in certain models, additionally verify whether they are required to appoint an authorised representative. Environmental compliance should therefore continue to be monitored after market entry rather than treated as something that can simply be checked off before the first sale.
Products and documentation
The second layer concerns obligations relating to the product itself. A company should establish whether the goods require specific labelling, instructions, warnings, declarations of conformity, or additional documentation, and in which language the relevant information must be made available to consumers. Not all products are subject to the same rules, which means the analysis should be carried out at the level of specific categories and, in some cases, even individual SKUs. Particular attention is required in sectors such as electronics, toys, children’s products, cosmetics, and other goods subject to additional regulation. The fact that a product is legally sold in one EU country should not be treated as automatic confirmation that every element of the offer, documentation, and labelling is ready for sale in every other member state.
The GPSR has applied since 13 December 2024 and has direct relevance to e-commerce and distance selling. Online offers need to include required information relating, among other things, to product identification, the manufacturer, relevant warnings, and, where applicable, the responsible person in the European Union. Language requirements must also be considered. Required information needs to be available in a form that consumers can understand in accordance with the rules applicable in the relevant market, while individual countries may impose their own language requirements. France is a good example of a country where the local language has legal as well as marketing significance when certain product information is presented. Product catalogue localization should therefore be managed together with the compliance process rather than as a separate marketing project.
Why does the UK need a separate process?
The United Kingdom requires a separate process because sales from the EU to Great Britain are not intra-EU sales. The intra-Community distance sales and OSS mechanisms do not apply in the same way as they do to sales between EU member states. Goods leave the European Union and are imported into the United Kingdom, which means border formalities, UK VAT, potential customs duties, product classification, and the way the import process is organized all need to be taken into account. Shipment value also matters, as does whether the sale takes place directly or via a marketplace. Under the current model, consignments worth up to GBP 135 may be subject to a different VAT mechanism from consignments above that threshold, while in certain cases responsibility for accounting for VAT may shift to the platform.
At the same time, the current rules should not be treated as a fixed model for the years ahead. In July 2026, the UK government confirmed a reform of the Low Value Imports system that is intended to remove the current customs duty relief for consignments worth up to GBP 135 and introduce a new customs framework no later than October 2028. Companies should therefore check the rules in force at the time they actually enter the market rather than rely on calculations prepared several years earlier. In practice, this means that tax and compliance are not one-off tasks completed before expansion. A company needs a process for checking registrations, VAT, EPR and obligations related to products before launch, and then updating them as the logistics model, product range, or local regulations change.
Which market should you choose? 4 scenarios instead of one ranking
There is no single market-entry sequence that will be right for every online store. The same country can be an excellent next step for a company selling a lightweight, high-margin product and a poor choice for a business selling bulky goods with low margins. Instead of looking for a universal ranking, it is therefore better to start by defining what problem the expansion is supposed to solve. For one company, the priority may be gaining experience in a market that is as simple to operate as possible. For another, it may be reaching customers who are willing to pay a higher price, while for a third it may be minimizing the cost of the first test. Only then does it make sense to use the scoring model discussed earlier and check which country best matches the specific scenario. This way of thinking matters more than the order of the countries itself because it allows the decision to reflect the product, margin, logistics, category, and resources the company actually has.
If you are just starting your expansion
For a company making its first serious move into another European market, one possible strategy is to increase complexity gradually rather than follow a fixed sequence of countries. The first market may be one that can be served efficiently from the company’s existing EU warehouse and logistics network, followed by another market where some of the same regional processes can be reused. Only later might the company move into markets requiring deeper localization, greater operational adaptation, or a separate import and customs model. For a Central European seller, for example, the Czech Republic or Slovakia may offer a relatively manageable regional test, while a company based elsewhere in the EU may find Germany, France, the Netherlands, or Poland operationally closer to its existing setup. Great Britain adds a separate import, tax, and customs layer regardless of where within the EU the seller is established.
This type of gradual path only makes sense if it fits the economics of the specific business. A high-margin brand with confirmed demand in Germany should not choose a smaller neighbouring market solely because it appears easier from a logistics perspective. Likewise, a company with years of experience selling outside the EU and well-developed import processes does not need to go through several additional EU markets before testing Great Britain. The sequence should result from the earlier scoring model, an assessment of unit economics, and the cost and time required to obtain reliable data. If a smaller or geographically closer market performs poorly in terms of demand or margin, operational simplicity alone is not enough reason to invest in it before entering a larger market that is better suited to the product.
If you are a premium brand
For a premium brand, Germany, France, the Netherlands, or the United Kingdom may score highly if category-level analysis confirms demand and the achievable price level allows the company to maintain its positioning and a healthy margin. The “premium” label alone, however, says too little to create one universal order of entry. The potential will look different for a fashion brand, a home furnishings manufacturer, a cosmetics company, a sports accessories business, or a specialist electronics seller. For products whose value comes from design, quality, brand, or specialization, market size and delivery costs are not the only important factors. The ability to justify the price, the way the product is presented, and the quality of the entire shopping experience become equally important.
Germany may be attractive because of its scale and strong logistics links with many EU markets. France may suit products whose value is strongly tied to brand, aesthetics, or communication. The Netherlands may fit companies with a mature cross-border model and an efficient process for localizing checkout. The United Kingdom, meanwhile, may justify the additional operational complexity if the product has enough margin to absorb import, service, and return costs. A premium brand should therefore not choose a market based on the general wealth of the country. In the scoring model, it makes more sense to give greater weight to achievable price, strength of positioning, demand within the specific category, and the quality of the shopping experience, and only then compare those advantages with the cost of entry.
If operational simplicity matters most
If the company wants to limit the number of new processes, it should first look for markets that can be served from its existing EU warehouse without immediately building local stock, a separate logistics structure, or a dedicated team. In this scenario, geographical proximity can have real value, but not because a neighbouring country is automatically easier from a marketing perspective. The advantage comes from being able to reuse some of the existing fulfilment, warehouse processes, integrations, analytics, and returns infrastructure. A nearby EU market may therefore look attractive when the current setup allows a test to be launched quickly without high fixed costs and without moving inventory into the target country.
Operational simplicity should not, however, mean minimal localization. Even when shipping from another EU member state, the company still needs to adapt language, currency where relevant, payments, delivery, terms and conditions, and relevant compliance elements. In a typical model where goods remain in one EU country and are sold to consumers in another, the sales may qualify as intra-Community distance sales, while OSS may help avoid local VAT registrations arising solely from those sales. A cross-border warehouse model can therefore be simpler from a tax and organizational perspective than local fulfilment, but this is not a rule that applies automatically in every situation. If delivery times or return costs begin to constrain sales as scale grows, local stock may become justified despite the added complexity. The goal is therefore to find a model that can generate reliable data with as few new processes as possible, not a market where nothing needs to change.
If you want to validate sales first
In many models, it is safer to start with a limited group of products that already have proven demand, healthy margins, and predictable return rates in the company’s existing markets. This is not a rule for every e-commerce business, because in some categories assortment breadth is itself an important part of the value proposition. If the company does not need thousands of SKUs for the offer to be attractive, however, limiting the catalogue makes the results easier to interpret. The business can select bestsellers or products that best represent the brand’s competitive advantage, prepare full localization for them, and test whether the value proposition itself works in the new market. With a full catalogue, it becomes much harder to determine whether weak performance results from lack of demand, poor pricing, problems with specific products, or an underdeveloped promotional strategy.
Before launch, the company also needs to define how it will know whether the test has succeeded. The number of orders alone is not enough. It should monitor customer acquisition cost, conversion rate, average order value, contribution margin, return rate, and the cost of maintaining the market. An equally important element is a pre-defined stop condition for the test. Without one, it is easy to finance sales for months even when they generate revenue but do not move closer to the expected level of profitability. Only when a limited offer demonstrates that customers can be acquired repeatedly at acceptable unit economics does it make sense to increase the budget, expand the catalogue, and invest in more developed local infrastructure.
How to calculate whether entering a market will pay off
The most common mistake when evaluating expansion is comparing the product price with advertising and shipping costs. In reality, entering a new market adds many more cost items, and some of them behave very differently as order volume increases. It is therefore worth separating the calculation into two levels. The first answers the question of whether each additional order contributes money to the business. The second shows whether the total margin generated by all orders is sufficient to cover the fixed costs of maintaining the market as well. Only by combining these two perspectives can you assess whether a new market is genuinely profitable.
Start with contribution margin per order
The starting point should be the net selling price, meaning the amount after VAT rather than the gross price seen by the consumer. This is particularly important in cross-border sales because the VAT rate applicable to a transaction may depend on the country of consumption. The same gross price may therefore leave the company with a different net amount in two different markets. From net revenue, you then need to subtract the cost of the product, customer acquisition cost, payment fees, fulfilment and delivery, expected return costs, sales-channel commissions, and other variable costs. The result is the contribution margin, which shows how much the average order contributes towards covering fixed costs and generating profit.
Net selling price – product cost – CAC – payment costs – fulfilment and delivery – expected return costs – sales-channel commissions – other variable costs = contribution margin per order.
Return costs should be understood more broadly than the price of the return shipping label alone. Depending on the category, they may also include parcel handling, product inspection, restocking, repackaging, loss of product value, and, in some cases, the cost of an item that can no longer be sold as new. The entire cost does not need to be assigned only to orders that are actually returned. If the company knows its average return rate, it can estimate the expected return cost allocated statistically to every order. This prevents country comparisons from artificially favouring a market where sales initially look strong but a large part of the margin disappears several weeks later through reverse logistics.
Then calculate the performance of the entire market
The second level covers costs that cannot reasonably be assigned directly to each individual product. These may include store localization, maintaining local content, compliance registration and reporting, integrations, advisory services, additional customer support, or fixed technology costs. Some will be one-off launch costs, some recurring monthly expenses, and others will increase in steps as the business scales. For this reason, it makes little sense to force all of them into one long per-order formula. First, determine how much contribution margin the sales generate, and then check whether the total amount is sufficient to cover the costs of maintaining the market.
Total market contribution margin – fixed and semi-fixed market costs = market result.
This distinction answers two different management questions. The first is: does another order improve the company’s financial result, or does it already generate a loss at the unit economics level? The second is: are there enough of these orders for the country as a whole to cover localization, compliance, and service costs as well? A market may have very good unit economics and still be unprofitable if sales volume remains too low relative to fixed costs. The opposite can also happen: high revenue may conceal a weak margin per order, which becomes a serious problem as marketing spend increases further.
Calculate VAT from the correct base
When modelling profitability, it is always worth comparing revenue excluding VAT. In B2C sales to different countries, the VAT rate applicable to the transaction can affect the net amount remaining from the same gross selling price. Within the EU, cross-border B2C sales from a warehouse in one member state to consumers in another may fall under the rules for intra-Community distance sales and be reported through OSS when the relevant conditions are met. If the company moves its own inventory to a warehouse in another EU country, additional local registration and reporting obligations may arise. Margin calculations should therefore use the actual net amount applicable to the chosen sales model rather than treating a fixed gross price as company revenue.
This can affect pricing decisions. If a business wants to maintain the same gross price in several countries, different VAT rates can result in different net revenues and therefore different margins. Alternatively, the company may set different gross prices for individual markets, but it then needs to check whether those prices remain competitive locally. VAT is therefore not purely an accounting issue settled after the sale. It should already be included when modelling pricing, margins, and discount levels for a specific country.
Calculate the market break-even point
Once the average contribution margin per order and the monthly fixed costs associated with the market are known, the break-even point can be calculated. The simplest model is to divide monthly fixed costs by the average contribution margin generated by one order. If maintaining the market costs EUR 6,000 per month and the average order leaves EUR 20 in contribution margin, the company needs around 300 orders per month to cover those costs. Only orders above that level begin to generate a positive result under this simplified model.
Break-even point in orders = monthly fixed market costs / average contribution margin per order.
This metric is particularly useful when comparing a large but expensive market with a smaller market that is cheaper to operate. The second country may require significantly fewer orders to reach profitability despite having lower potential revenue. On the other hand, a high break-even point does not automatically disqualify a large market if realistic sales volumes are expected to exceed it several times over. The number should therefore always be considered alongside demand forecasts, marketing capabilities, and the company’s operational constraints.
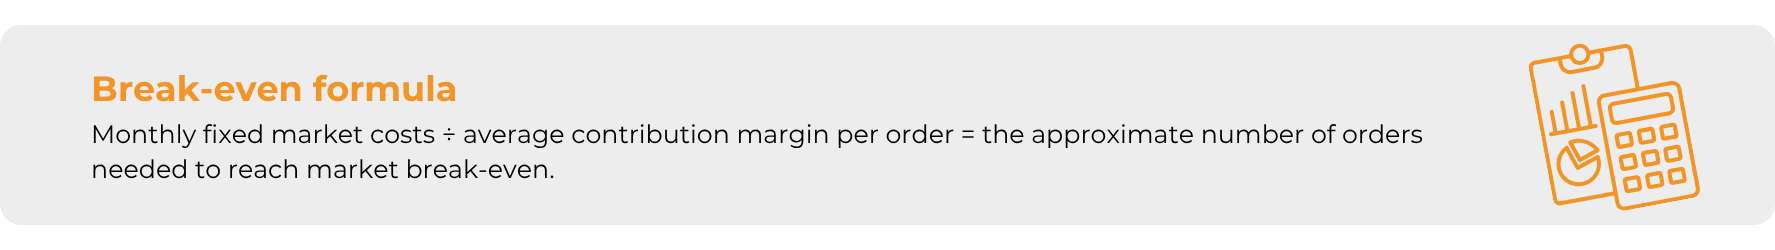
Also test a less optimistic scenario
The calculation should not be based on a single scenario. A market may look excellent at the assumed CAC, return rate, and average order value, but stop making financial sense after a relatively small deterioration in one of those parameters. Alongside the base case, it is therefore worth modelling a scenario where customer acquisition is more expensive, the return rate rises, a lower selling price becomes necessary, or delivery costs turn out to be higher than expected. If changing one parameter immediately takes the model from an attractive margin to a loss, the company has very little room for error or for the learning period that usually comes with entering a new market.
The final question remains simple: after all costs are included, does the expansion actually make money, or does it merely generate international revenue? If the answer depends on excluding VAT, returns, localization, compliance costs, or part of the marketing spend, the calculation does not reflect the true situation. A good next market should generate both a positive contribution margin per order and enough scale to cover the cost of maintaining the market. Only then does international sales stop being an experiment financed by the rest of the business and become an independent, scalable source of profit.
Checklist: 10 questions before entering a new market
Before launching sales, it is worth going through one final readiness check and verifying whether the most important assumptions have already been confirmed with data or are still based mainly on intuition. The point is not to know the answer to every possible question before the first order comes in. The goal is to separate the risks the company consciously accepts as part of the test from problems that could have been identified before spending budget on campaigns and localization. If the answer to several of the questions below is “we don’t know”, the market is probably not ready to scale yet. In that case, it is better to complete the analysis or narrow the scope of the test than to build a full local operation immediately.
Do we know who we will really be competing with?
A list of a few of the largest brands is not enough. The company should know which offers customers will see next to its product, which channels they will use to compare them, what prices are actually available, and where competitors build their advantage. The analysis should cover not only the product itself, but also delivery costs, fulfilment times, return policies, the way the offer is presented, and the level of localization. It is particularly valuable to look at the market from the customer’s perspective and go through the purchasing process with several competitors. This shows which standards the company at least needs to match and where it can realistically offer something better. If the only visible advantage is a lower price, the business should calculate before launch whether that model will still leave sufficient margin after marketing, delivery, and return costs.
Does the price leave a healthy margin after all costs?
The price displayed in the store says nothing by itself about the profitability of the market. The company needs to know the net amount after VAT, product cost, CAC, sales-channel commissions, payment fees, fulfilment, delivery, and the expected cost of returns. Only then can the contribution margin be assessed. Fixed or semi-fixed costs related to localization, compliance, market support, and integrations should be included separately. It is also worth modelling a less favourable scenario than the planned one: higher advertising costs, more returns, or the need to use promotions. If the market economics only work under optimistic assumptions, the company has very little room for learning and mistakes. A good test should show not only that orders can be generated, but also that every additional order contributes enough margin to cover the cost of maintaining the market.
Does the checkout match local payment habits?
Payments should be verified before campaigns begin, not only after traffic is high but conversion turns out to be disappointing. The company needs to check which payment methods customers actually use in the market and whether the current store infrastructure allows them to be implemented without disproportionate cost. Currency, how prices are displayed, refund speed, and payment fees that affect order economics also matter. The Netherlands is a good example of how a local payment method can form an important part of the expected shopping standard, but the same analysis should be performed for every country. The question is therefore not “can the customer technically pay?”, but “does the checkout look and work the way a local customer expects?”. If the answer is no, the store may lose sales at exactly the point where the most expensive part of customer acquisition has already taken place.
Is delivery competitive, rather than merely possible?
Being able to send a parcel to a particular country does not mean the logistics model is good. The company needs to know the last-mile cost, realistic delivery time, available collection options, and how failed deliveries are handled. Customers compare the offer not with other cross-border sellers using the same origin market, but with the alternatives available to them locally. If local sellers offer more convenient collection or shorter delivery times, that difference may affect conversion. At the same time, there is no need to assume immediately that a local warehouse is necessary. In the first phase, shipping from an existing EU warehouse may be sufficient, particularly for lightweight, high-margin products. The data should determine whether local fulfilment actually improves economics and customer experience enough to justify the additional costs and potential tax obligations.
Does localization cover the entire purchasing process?
Localization does not end with the product page. Before launch, the company should review the checkout, delivery terms, returns policy, terms and conditions, FAQ, transactional messages, advertising, and customer service. It is equally important to check whether the language sounds natural and whether the sales arguments match the way the product is positioned in that market. In some countries, the local language also has legal significance when required product information is presented. The company should therefore distinguish between two levels: the minimum required for compliant selling and full commercial localization designed to improve trust and conversion. If the market requires much more content, customer service, and ongoing updates than expected, those costs must be reflected in the financial model, because after launch localization becomes an ongoing process rather than a one-off translation project.
Do we know how much a return really costs?
A return should be treated as part of order economics, not as an exception dealt with only when the customer sends a product back. The company needs to calculate return shipping, parcel handling, product inspection, repackaging, restocking, and the potential loss in product value. It is also worth determining whether a local return address makes business sense, whether the product can be returned directly to the company’s existing EU warehouse, and how long it will remain unavailable for sale in that case. This is particularly important in categories where returns are a significant part of the business model. Even an attractive price and strong conversion do not guarantee profitability if a large share of the margin disappears several weeks later in reverse logistics. The expected cost of returns should therefore be allocated to every order before potential markets are compared.
Does the VAT model reflect where the goods are actually located?
Before the first sale, the company should map the exact flow of goods. If stock remains in one EU member state and is shipped from there to consumers in other EU countries, the rules on intra-Community distance sales need to be analysed, including the EU threshold of EUR 10,000 for transactions covered by it and the possibility of accounting for VAT due in the countries of consumption through OSS. It should not be assumed that OSS only becomes available once that threshold is exceeded. The key is to determine where, under the chosen sales model, the obligation to account for VAT arises and whether OSS can be used to handle it.
The situation changes when the company moves its own inventory to a warehouse in another EU country. Such a transfer may itself create VAT obligations connected with the movement of the company’s own goods, while subsequent local sales are generally not intra-Community distance sales. Local fulfilment should therefore be analysed before the inventory is moved, not only after sales have started. Great Britain requires a separate process because sales from the EU involve export and import, and EU OSS is not used to account for UK VAT. The most important question is therefore not “which country are we selling to?”, but “where exactly does transport begin, where is the inventory located, and what type of transaction are we actually carrying out?”.
Have we checked compliance for the specific product and country?
VAT is not the only obligation. The company should review EPR, packaging, product safety, required labelling, warnings, documentation, and the information that must be displayed in online sales. The scope depends on both the country and the category. A product may be subject to additional requirements because it is electronic equipment, contains a battery, is a toy, a cosmetic product, or belongs to another regulated group. The GPSR has also applied since 13 December 2024 and is relevant to information displayed in distance-selling offers, including online. Depending on the situation, this may include manufacturer details, product identification, appropriate warnings, and information relating to the responsible person in the EU.
The company should therefore not assume that because a product is legally sold in one EU member state, the entire catalogue is automatically ready for international expansion. Before launch, it needs to establish which obligations apply to specific SKUs and whether all required registrations, documents, and data are available. For a larger catalogue, it is also worth identifying which groups of products have a similar regulatory profile and which require separate analysis. This helps avoid a situation where the company launches the entire assortment and only later discovers that some products require additional registrations, labelling, or changes to the information shown to customers.
Have we chosen the right sales channel?
Not every product should begin its expansion through the company’s own store, and not every market should be tested exclusively through a marketplace. The company needs to check where customers in the category discover products, compare offers, and complete purchases. In some models, a marketplace can speed up demand testing, but this does not automatically mean lower entry costs or simpler compliance. There may be commissions, advertising costs within the platform, fulfilment and return requirements, documentation requirements, and in some cases registration numbers or product data may be required before the offer can even go live. An own store gives the company more control over the brand, pricing, and customer relationship, but requires it to build traffic and trust independently. The right channel should therefore be chosen based on the category, local customer behaviour, and sales economics rather than the assumption that one model is always best.
Do we know when we will consider the test a success, and when we will stop it?
A test without defined success criteria can easily turn into a project with no end point. Before launching the market, the company should establish which results will justify increasing investment and which will show that the hypothesis has not been confirmed. The key metrics to monitor include CAC, conversion, AOV, contribution margin, delivery cost, return rate, and the total cost of maintaining the market. Not every metric needs to reach its target value in the first month, but the company should know how long it is prepared to finance the learning period and what improvement it expects at each stage. An exit condition is equally important. If, after a defined budget, number of orders, or testing period, the market still does not move closer to economics that support scaling, stopping the project may be a better decision than continuing to invest simply because the company has already incurred the entry cost.
How to make the final decision
After going through the checklist, the number of potential markets should be significantly smaller. At this stage, there is little value in returning to the general question of which country is the largest or has the greatest potential. The decision should come from the economics, the scoring model, and the ability to run a meaningful test within a reasonable timeframe and budget. The order matters: first eliminate markets where the basic unit economics do not work, and only then compare the attractiveness of those that remain. Scoring should not be used to rescue a market where every additional order generates a loss.
- Eliminate markets where the unit economics do not work. If the realistic net selling price does not cover the product, CAC, payments, logistics, commissions, and expected return costs, market size will not solve the problem. The model needs to be improved first, or a different country should be selected.
- Score the remaining markets from 1 to 5. Compare demand, margin, competition, logistics, payments, compliance, and ease of localization, using the same assessment rules for every country.
- Limit the number of markets tested at the same time. For many companies, it is better to collect reliable data from one or two markets than to localize five countries simultaneously. This makes it easier to understand the reasons behind the result, improve the process faster, and identify more precisely whether the problem lies in the product, pricing, marketing, or operations. A company with a larger team and mature infrastructure can, of course, run more tests in parallel if it can measure them separately without compromising execution quality.
- Launch a controlled offer. If the business model allows it, start with products that already have proven demand and healthy margins rather than moving the entire catalogue before the first meaningful data is available.
- Compare actual results with the assumptions. Check the real contribution margin, CAC, conversion rate, AOV, return rate, logistics costs, and operating costs. It is particularly important to compare actual data with the assumptions previously used in the scoring model.
- Only then decide whether to enter the market fully. If the test shows repeatable demand and economics that can also cover the market’s fixed costs, the company can expand the catalogue, increase the budget, and consider additional infrastructure. If the numbers do not work, stopping the project early is a valid business decision, not a failure of expansion.
This process reduces the risk of making a decision based on a single metric. A market may have strong demand but weak margins. It may also initially generate expensive orders, but perform much better after the checkout is localized and logistics are improved. The most important step is therefore comparing the original hypothesis with actual data. Only then can the company determine whether the problem requires optimization or whether the market itself is a poor fit for the product.
Summary: the best market is not always the largest market
Choosing the next e-commerce market should not begin with a table showing where consumers spend the most online. That information can help create a shortlist of potential destinations, but it does not answer the most important question for the business: where can my specific product be sold profitably? The answer requires combining demand with achievable pricing, competition, marketing costs, logistics, payments, returns, localization, VAT, and compliance. Only then can you see whether a large market is genuinely a major opportunity for the company or simply a place where it can generate a large amount of expensive revenue.
Germany may be attractive for a company with a strong product and well-organized processes, the Czech Republic can work well as a controlled regional expansion test, and Slovakia may allow the company to make use of some regional synergies. France may require greater investment in localization and compliance, the Netherlands clearly demonstrates the importance of adapting checkout to local payment methods, while selling to Great Britain requires a separate tax and import model. Poland, meanwhile, can be attractive for businesses that can adapt to strong price transparency, local payment habits, and well-developed out-of-home delivery. None of these countries is automatically first or last. The right order depends on the category, margin, logistics model, existing infrastructure, and organizational capabilities of the specific business.
The best next market is not the country with the largest number of online shoppers. It is the market where the product has confirmed demand, the checkout matches local expectations, logistics are predictable, obligations are under control, and a positive margin remains after all costs. If one of these elements is still unknown, that does not always mean the market should be rejected. It does mean, however, that before making a full commitment, it is worth designing a test that resolves that uncertainty as cheaply and quickly as possible.
VAT and environmental obligations should be verified particularly early because incorrect assumptions in these areas are difficult to fix through campaign or checkout optimization alone. A sales model based on shipping from an existing warehouse in one EU member state may have different consequences from local fulfilment in the target country, while EPR obligations may vary by country and product category. Before launching another market, it is therefore worth checking not only whether demand exists, but also which registrations, VAT settlements, and EPR obligations will arise from the planned sales model. At this stage, support from amavat can help organize VAT obligations and selected compliance requirements related to expansion before the company makes a full investment in the new market.
Important: the information provided in this material is general and informational in nature. It does not constitute legal, tax, or accounting advice and should not be treated as a recommendation for any specific sales model. Obligations relating to VAT, EPR, cross-border sales, warehousing, or product compliance may depend on the country, product category, distribution model, and the individual circumstances of the business. Before entering a new market, the applicable rules and requirements should always be verified for the specific case.